
Stocks & investing
10 Best Free Investing Tools for Beginners (2026)
10 free investing tools for beginners: calculators, fee checkers, company filings, charts, screeners, trackers and a practice app, with each tool's limits.
Diversifying means spreading your money so one bad investment can't sink you. Learn to spot hidden overlap, map what you own and keep your mix on track.

Diversify by industry, country and type of investment, not just by number of holdings.
To means to spread your money so that no single investment decides your result. If one company has a terrible year, the rest of your money can soften the blow.
It works because different businesses react differently to the same news. When the price of oil jumps, an airline pays more for fuel, while an oil producer may earn more. Own both, and one can partly make up for the other.
A bigger choice comes first: how much to keep in shares, and cash. This is called . It should match when you need the money and how big a fall you could live with. The SEC, the US markets regulator, explains this in its guide to asset allocation.
| Type | What it is | How much it usually moves |
|---|---|---|
| Shares | Part-ownership of companies | A lot, up and down |
| Bonds | Loans to a government or company that pay interest | Usually less than shares, but they can lose value |
| Cash and savings | Money in the bank or very short-term loans | Very little, but it may not keep up with rising prices |
Diversifying lowers the damage from one bad investment. It does not stop every loss. Many investments can fall at the same time.
Not always. Count what you are exposed to, not how many names you own. A broad US share fund, a technology fund and a few tech company shares can all depend on the same big companies.
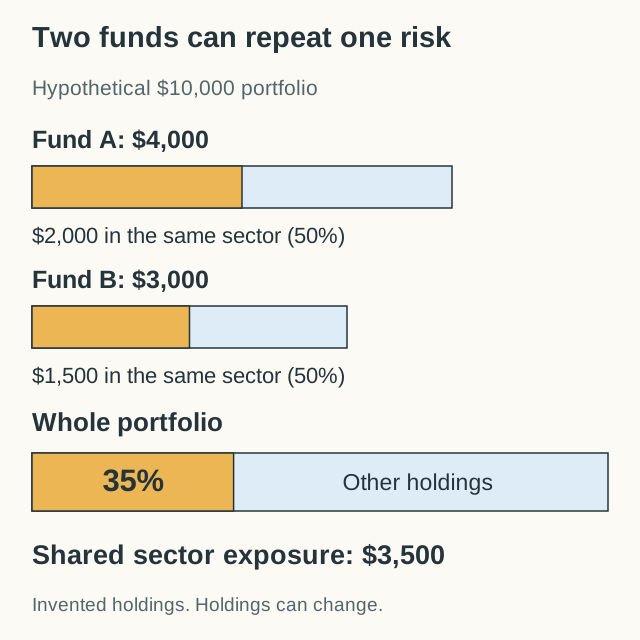
Each fund lists its holdings on its website or in its documents. Check the biggest ones, and look for the same names appearing in more than one fund.
Try it yourself
Pick up to 6 made-up companies for a $1,000 basket. Press "Something happens" and see your result. Then try three tech companies, and then six different industries.
With $1,000 in three tech companies, the first event, a tech sell-off, costs 30% and leaves $700. One company from each of six industries loses about 5.3% and keeps about $947. In the third event, a recession scare, every company falls, so every basket loses.
What would you expect?
What this shows: Owning different industries softens a single shock. Three tech companies are still one bet, and a market-wide fall still hurts every basket.
Each shock hits some industries hard and others little. Companies in the same industry fall together, so only real differences help. When the whole market falls, spreading makes the drop smaller but cannot stop it.
Make a simple map of your money. Write down each :
| Look at | What to write down |
|---|---|
| Types of investment | Shares, bonds, cash and anything else |
| Inside your shares | Countries, industries and company sizes |
| Inside your bonds | Who borrowed, for how long, how safe, which currency |
| Biggest holdings | The largest companies, including those inside funds |
| Costs | Fund fees, trading costs and taxes |
Try it with a $1,000 practice budget. Put $500 in a broad fund that is 30% technology. Put $300 in a technology fund and $200 in one technology company. Your technology exposure is $150 + $300 + $200 = $650, or 65%.
Check company size too. Many broad indexes, the lists of shares that funds follow, are weighted by market cap. That gives the biggest companies the biggest weight. So a fund that holds hundreds of companies can still have a large share of your money in a handful of giants.
Repeat the map for country and currency. A Canadian who owns mostly US shares also carries the risk of the US dollar falling against the Canadian dollar. See currency risk for Canadian investors.
Your mix changes even if you do nothing. Say two holdings start at $500 each. One rises to $600 and the other stays at $500. The first is now 54.5% of your $1,100, not 50%. This is called .
means moving back to your planned mix. Suppose you planned 60% shares and 40% bonds on $10,000. After a good year for shares, you hold $7,000 in shares and $3,000 in bonds. That is 70/30. Moving $1,000 from shares to bonds brings you back to 60/40, before costs and tax.
Selling can cost fees and, in some accounts, tax. A review does not have to end in a trade.
Diversification cannot turn a short deadline into a long one. It cannot promise a return, and it cannot stop a fall in the whole market.
Adding something risky just because it is "different" can add risks you don't understand. For each holding, ask what job it does and what could make it fall.
You can also overdo it. Ten funds that own the same companies add work, not safety. A few broad funds you understand can spread your money more than many narrow ones.
Last, ask whether a fall would hurt money you need soon. A school fee due next month and a retirement decades away are different jobs. Next lesson: comparing brokerage fees, because costs are the one part of your mix you control. Or read about buy and hold investing.
There is no magic number. What matters is how different the holdings are. Ten companies in one industry are less diversified than one broad fund that holds hundreds of companies across many industries and countries.
A broad fund can spread your money across many companies in one step. Check what it holds: some indexes lean heavily on their biggest companies, one country or one industry. You may also want bonds or cash, depending on your goal.
Yes, in a way. Owning many funds that hold the same companies adds work and costs without adding much safety. A few broad funds you understand can do more.
Pick a rule and stick to it, such as once a year, or when a part drifts more than a set amount from its target. Remember that selling can cost fees and tax.
10 free investing tools for beginners: calculators, fee checkers, company filings, charts, screeners, trackers and a practice app, with each tool's limits.
10 well-known dividend stocks, from Coca-Cola to Main Street Capital: their dividend records, risks and how to check them. A research list, not buy tips.